When clients share their tax documents with you, they expect that information to be used to prepare their returns. But what happens when someone else needs access to those records, or your firm wants to use the information for another purpose?
Section 7216 of the Internal Revenue Code sets rules for when tax preparers can use or disclose client tax information without consent and when written permission is required. The requirements can affect everyday tasks, including working with outside service providers or overseas teams.
Understanding when consent is necessary helps you avoid unnecessary paperwork while keeping your client onboarding process compliant.
Clients may sign a page titled Consent to Use of Tax Return Information, or Consent to Disclosure of Tax Return Information. Many people call it Form 7216, but the Internal Revenue Service (IRS) has no form with that number.
The name comes from section 7216 of the Internal Revenue Code (IRC), also written as IRC 7216. Under that section, knowingly or recklessly sharing a client’s information, or using it for anything but the return, is a crime. The law and its regulations list exceptions, and anything outside them needs the client’s written consent.
Tax return information is anything you receive to prepare the return, even the client’s name and address. It also covers what you work out from it while preparing the return (Treasury Regulation 301.7216-1).
A use means relying on that information to take an action. Using a return to decide which clients to ask about an individual retirement account (IRA) is one example. A disclosure means making it known to anyone, in any way.
A client does not need to sign a consent just to have their return prepared (Revenue Procedure 2013-14, section 2). Other tasks depend on the exceptions in Treasury Regulation 301.7216-2. What matters is who gets the information, where they are and why.
|
Task |
Consent needed? |
Treasury Regulation |
|---|---|---|
|
A colleague in your US office works on the return |
No |
301.7216-2(c)(2) |
|
A US processing or e-file service handles the return, making no tax decisions |
No |
301.7216-2(d)(1) |
|
Your accounting firm uses the information to keep the same client’s books |
No |
301.7216-2(h)(1) |
|
Your staff or a contractor outside the United States works on the return |
Yes, business clients included |
301.7216-2(c)(2), 301.7216-3(a)(3)(i)(D) |
|
Another firm advises on the return, such as on a deduction |
Yes |
301.7216-2(d)(1) |
|
An affiliated firm, such as a financial planning firm in your group, gets it for its own work |
Yes |
301.7216-2(h)(1)(ii) |
|
You use the information to offer loans, investments or insurance |
Yes, naming each type of product |
301.7216-3(a)(3)(i)(B) |
Every consent needs the same core details. Consents for individuals filing a return in the Form 1040 series need more.
For any client, a consent must include these (Treasury Regulation 301.7216-3(a)(3)(i)):
A consent to disclose the whole return must also say the client can ask you to share less.
For clients who file a Form 1040, Revenue Procedure 2013-14 fixes part of the wording. Each type of consent must include the statements it lists, word for word and in the order given (section 5.04(1)). You may put your firm’s name in place of “we” and “our”.
The statements explain why the client is getting the form and that they do not have to complete it. Every consent also says how to report misuse to the Treasury Inspector General for Tax Administration (TIGTA).
Sharing with a preparer outside the United States needs one more statement. If the Social Security number is not masked, both preparers must also have an adequate data protection safeguard. That is a security program, approved by management, that meets a privacy or security framework listed in section 5.07.
For Form 1040 filers, a single consent form cannot cover every way you use or share their tax information. Consent to use and consent to disclose must be handled in separate written documents, although you can attach both to the engagement letter (section 5.01).
You can include several uses or several disclosures in one document, as long as clients can choose which ones they agree to. However, you cannot combine uses and disclosures on the same form (Treasury Regulation 301.7216-3(c)(1)). Clients must also actively give their permission, so preselected checkboxes that require them to opt out are not allowed.
The presentation matters too. Paper consent forms must use letter-size or larger sheets, at least 12-point text, and no unrelated content on the page. For electronic forms, the text must be at least as large as the website’s normal font, easy to read against the background, and properly formatted for printing.
The rules are lighter for other clients, such as corporations and trusts. Their consent can take any format, including a section of the engagement letter (Treasury Regulation 301.7216-3(a)(3)(iii)). It still needs the core details listed above.
The fixed wording is optional, and uses and disclosures can share one document. The consent can also name a group of recipients, such as the client’s auditors.
For example, a corporation’s engagement letter can let its preparer share return details with the firm arranging its financing.
The signing methods below come from Revenue Procedure 2013-14, so they apply to Form 1040 filers. The rules on when to ask apply to every client.
A paper consent needs the client’s handwritten signature. An electronic consent must be signed in one of three ways, each typed by the client (section 6):
The software must not fill in the PIN or name, so a single click is not enough.
Do not leave blanks to fill in after the client signs, and do not change the consent once signed. Every client must also get a copy at signing, or the chance to print or save it then (Treasury Regulation 301.7216-3(c)(3)).
Timing is just as important as the consent itself. Clients must give permission before their tax information is used or disclosed, since a signed form cannot authorize something that has already happened.
There are also stricter rules when you want to use client information to offer products or services unrelated to tax return preparation. You must request this consent before presenting the completed return for signature. If the client refuses, you cannot ask again for essentially the same purpose for that return (Treasury Regulation 301.7216-3(b)).
Consent must also be knowing and voluntary, meaning clients understand what they are agreeing to and can refuse without losing access to your services. However, there is an exception when another preparer needs the information to help complete the return. If the client declines that disclosure, you may refuse the engagement or adjust its terms, including the fee.
A consent lasts for the period it states. If it states none, it lasts one year from the date the client signed it (Treasury Regulation 301.7216-3(b)(5)).
Keep the signed consent in the client’s file with its start and end dates. If you still need it after it ends, ask for a new one.
A use or disclosure the rules do not allow can lead to a criminal penalty, a civil penalty, or both. Under section 7216, doing it knowingly or recklessly is a misdemeanor.
A conviction can bring a fine of up to $1,000, up to a year in prison, or both, plus prosecution costs. If the use or disclosure is linked to an identity theft crime, the maximum fine is $100,000.
Under section 6713, the civil penalty is $250 for each disclosure or use. A preparer’s total is capped at $10,000 a calendar year. It applies even if the preparer did not act knowingly or recklessly.
When identity theft is involved, the civil penalty is $1,000 each, capped at $50,000 a year. The two caps are counted separately. These amounts are set by law and are not among the 2026 inflation adjustments in Revenue Procedure 2025-32.
A consent must come before the use, so onboarding is the natural time to collect it. List every way your firm uses or shares return information, such as with an offshore team. Then draft a consent for each one the exceptions do not cover.
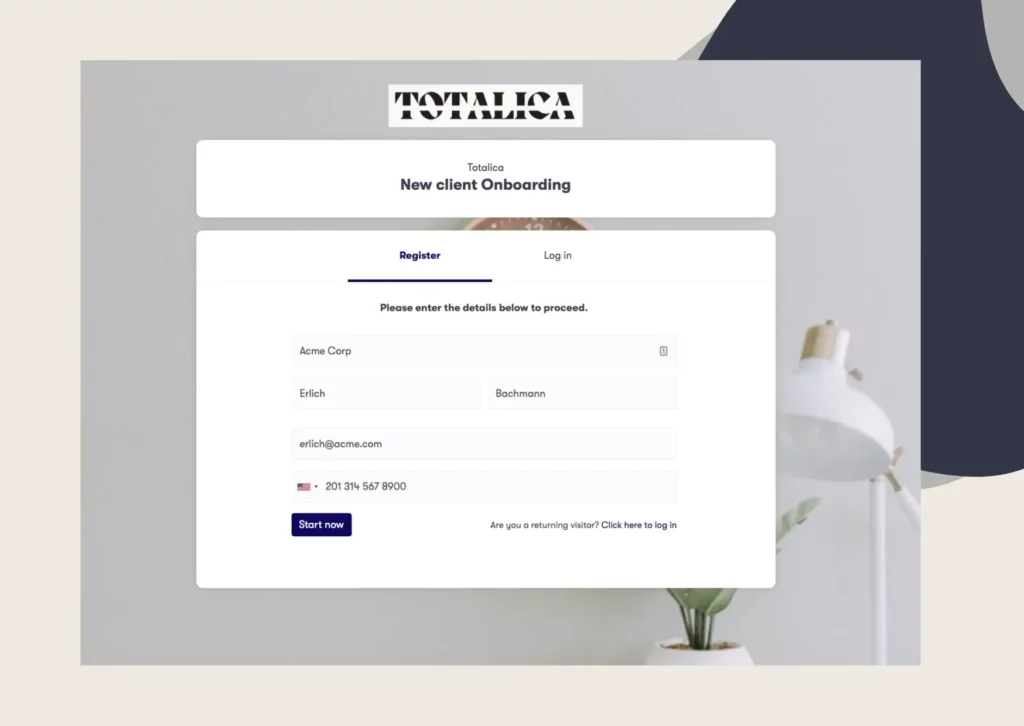
In client onboarding for accountants, the 7216 consent belongs with the other authorizations and agreements, such as the engagement letter.
Clustdoc lets you add several signature steps to one onboarding flow, based on each client’s profile. Only clients whose returns go to your offshore team then get the offshore consent, as its own signed document.
Our signature workflow lets you decide whether each signer receives the signed copy, so the client can keep theirs.
Book a demo call and show us the consent wording your firm uses today. Our team will suggest where each consent could fit in a Clustdoc onboarding flow.
No, the Internal Revenue Service (IRS) has no form with that number. The name usually refers to the consent a client signs under section 7216 of the Internal Revenue Code. It allows a specific use or disclosure of the client's tax return information beyond preparing the return.
In Revenue Procedure 2013-14, the examples are separate pages or screens, titled as a consent to use or to disclose. Each opens with the fixed statements. The client then checks a box beside a sentence naming the information and its purpose, and signs and dates it.
No, a consent must be voluntary, so a preparer cannot make any of their services depend on it. The exception is a consent that lets another preparer, such as an overseas team, help prepare your return. If you refuse that one, the preparer may decline the work or change its terms.
It is valid for the period it states. If it states none, it lasts one year from the date the client signed it. After that, the preparer needs a new signed consent to keep using or sharing it for that purpose.
Yes, but for Form 1040 filers the client has to type the signature in. It can be their name, or an assigned personal identification number of five or more characters. Five or more characters unique to them, which the preparer uses to confirm their identity, also work.
Still stitching emails, files, and approvals together?
Clustdoc gives teams one place to run client-facing work, boost customer engagement and increase compliance.
Claire writes about customer onboarding, digital processes, and the day-to-day challenges faced by operations teams. At Clustdoc, she focuses on practical insights: how organizations collect information, guide customers through complex steps, and improve service delivery with automation.